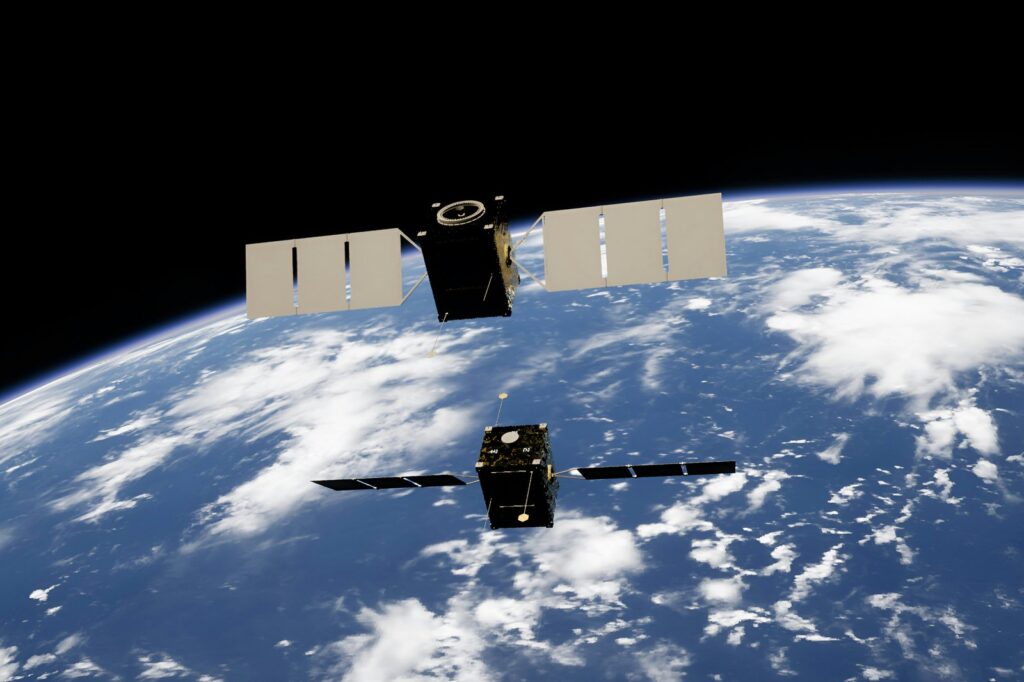
WASHINGTON, October 29, 2026 — The U.S. Space Force plans to award Boeing a sole-source contract worth up to $945.9 million to maintain and modernize military communications satellites and ground systems. The Department of Defense cited Boeing’s ownership of proprietary technical data and software as the justification for bypassing competitive bidding.
The Rationale Behind Sole-Source Military Contracting
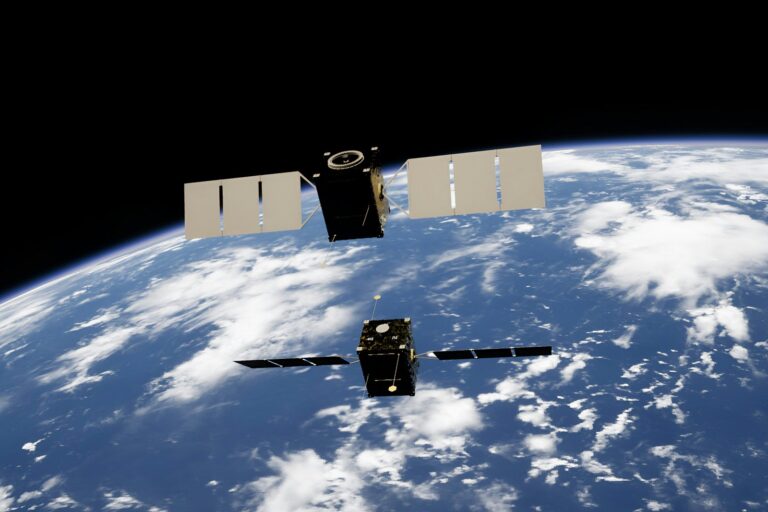
Sole-source awards are often necessitated when a single contractor holds the exclusive technical knowledge required for system upkeep, according to the Space Force announcement reported by SpaceNews. In this case, the Pentagon determined that Boeing’s proprietary control over the technical data and software underpinning the satellite constellation makes a competitive procurement impractical. The contract covers maintenance and modernization of military communications satellites and their associated ground infrastructure, locking in the prime contractor for the lifecycle of systems it originally built and continues to define.
The Role of Proprietary Data in Defense Maintenance
The technical reality of modern military space programs is that intellectual property rights often dictate the sustainment strategy. The Department of Defense justification rests on the fact that Boeing owns the proprietary technical data and software needed to perform the work. This ownership creates a structural barrier to entry for potential competitors, who would require access to source code, architecture documentation, and interface control documents that the government does not possess unlimited rights to use or disclose. As ever, the detail that matters is not the hardware in orbit but the intellectual property regime on the ground.
Boeing’s Historical Integration Into Space and Satellite Sectors
Boeing’s current gatekeeper position is the product of decades of consolidation. The company diversified into outer space travel during the 1960s and 1970s, establishing a foothold in the sector early. A pivotal expansion occurred in 2000 with the acquisition of the satellite segment of Hughes Electronics, which significantly broadened Boeing’s satellite manufacturing and communications portfolio. The 1997 merger with McDonnell Douglas further entrenched its defense and space capabilities, bringing legacy missile and space systems into the fold. Today, the company is organized into three primary divisions, including Boeing Defense, Space & Security, which manages these military space programs.
Implications for Competition in the Military Space Industry
The award highlights a persistent tension in defense acquisition: the government’s desire for competition versus the proprietary realities of complex systems engineering. Boeing is the fourth-largest defense contractor in the world based on 2022 revenue, and its massive global footprint as a major aerospace manufacturer and U.S. exporter reinforces its incumbent advantage. When the government purchases a satellite system, it often acquires the hardware but not the full technical data package required for independent sustainment. This dynamic effectively grants the original equipment manufacturer a monopoly on maintenance and modernization for the operational life of the constellation.
Financial Context of Boeing’s Defense and Space Division
The $945.9 million contract arrives as Boeing navigates a challenging financial period. The company recorded $62.3 billion in sales in 2021 and is ranked 54th on the Fortune 500 list. However, recent analyst actions reflect pressure on the broader enterprise. In late October 2026, multiple firms lowered price targets following third-quarter results and a revised free cash flow outlook. BofA Securities cut its target to $235 from $270 while maintaining a “Buy” rating, noting the turnaround story is “still intact” but that free cash flow projections for fiscal years 2027 and 2028 fall short of Street expectations by wide margins. JPMorgan and UBS also reduced targets, citing a slower path to normalized cash flow. The Space Force sole-source award provides a defined revenue stream for the Defense, Space & Security division amid wider commercial headwinds.
Broader Corporate Scope and Global Reach
Beyond its defense operations, Boeing maintains a significant presence as a multinational corporation involved in the design and manufacture of rockets, missiles, and rotorcraft. Founded in 1916 by William E. Boeing in Seattle, Washington, the company has evolved into the largest exporter in the United States by dollar value. Its corporate headquarters is currently located in the Crystal City neighborhood of Arlington County, Virginia, near Washington, D.C. The firm’s extensive infrastructure includes a global manufacturing footprint, such as its first European factory opened in 2018 in Sheffield, United Kingdom.
The company’s influence extends into various aerospace sectors, including commercial aviation and logistics. According to its 2026 World Air Cargo Forecast, Boeing projects that global air cargo traffic will double over the next 20 years. To support this growth and replace retiring aircraft, the company expects the worldwide freighter fleet to expand by 67%, increasing from 2,395 aircraft in 2025 to 4,010 by 2045. This commercial outlook complements the company’s long-standing history of diversification, which began in the 1960s when it expanded from its aviation roots into industries including energy production, transit systems, and marine craft.
Analyst Reactions and Market Impact
The financial community has responded with caution to Boeing’s latest developments, despite the company maintaining its “turnaround story” narrative. Following third-quarter results released in late October 2026, multiple firms lowered their price targets for the stock. BofA Securities cut its target to $235 from $270, while JPMorgan reduced its valuation to $240 from $290. UBS also adjusted its target downward to $240 from $275.
These adjustments reflect concerns that Boeing’s free cash flow projections for fiscal years 2027 and 2028 fall short of Street expectations by wide margins. Wells Fargo similarly lowered its price target to $210 from $250, though it maintained an ‘Overweight’ rating. Analysts noted that the path to normalized cash flow is taking longer than anticipated, even as production and certification progress continues.
Despite these reductions, Koyfin data indicates that 25 out of 28 analysts covering the stock still rate it either ‘Buy’ or ‘Strong Buy’. The consensus suggests the company may struggle to rebound fully before improvements in 737 MAX first flights and/or 777X certification materialize. Meanwhile, Boeing published its 2026 World Air Cargo Forecast, projecting that global air cargo traffic will double over the next 20 years.
Sources
- Boeing to be awarded sole-source deal worth up to $946 million to maintain military satellites
- Boeing
- Boeing Stock Hits Fresh 18-Month Low After Slew Of Price Target Cuts – BofA Says Turnaround Story Is ‘Still Intact’
Photo: Kevin Stadnyk / Unsplash (Unsplash License)