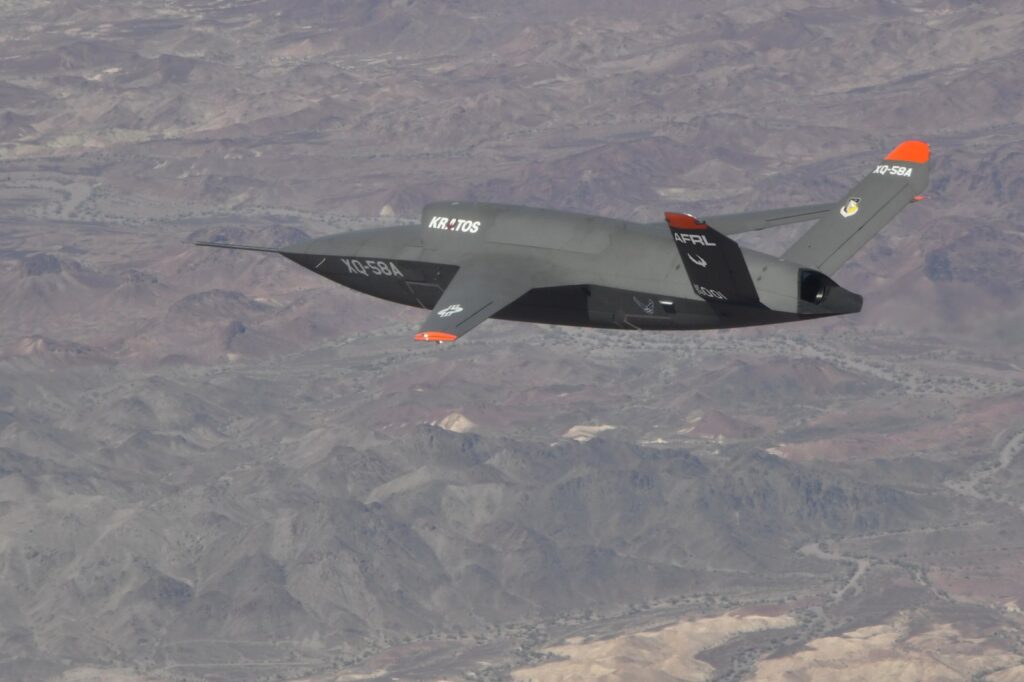
Kratos Defense & Security Solutions shares have lost 17.1% over the past month, a slide that far outpaces the Zacks Aerospace-Defense Equipment industry’s 2.9% decline. The drop comes even as the San Diego-based contractor posted record third-quarter bookings and a backlog that topped $2.6 billion.
Record Quarter, Cautious Outlook
Kratos reported third-quarter 2026 revenue of $471.8 million, up 35.7% year over year, with organic growth of 23.2%. Adjusted EBITDA came in at $50.9 million, or 10.8% of revenue. Bookings hit $1.04 billion, driving a book-to-bill ratio of 2.2-to-1 and pushing the consolidated backlog to a record $2.6 billion as of September 27, according to the company’s earnings release.
President and CEO Eric DeMarco said the company’s internal forecast for 2027 was “considerably higher” than the published outlook of $2.1 billion to $2.2 billion in revenue. Management trimmed the public guidance, citing the federal continuing resolution, a new Congress and supply chain constraints. The company also projected 2027 adjusted EBITDA of $230 million to $240 million.
For the current year, Kratos tightened 2026 revenue guidance to $1.78 billion to $1.81 billion. Fourth-quarter revenue is expected between $480 million and $510 million, implying organic growth of 18% to 26% from the prior-year period.
The Procurement Overhang
The technical reality is that Kratos sits at the sharp end of the Pentagon’s shift toward unmanned systems and hypersonics, yet its share price is moving on budget mechanics, not capability. The continuing resolution freezes new starts and caps spending at prior-year levels, a particular drag for a company winning low-rate initial production contracts that need funding ramps to scale.
DeMarco noted the company does not need a reconciliation bill to meet its 2027 objectives, but an appropriation by March 31 and a subsequent reconciliation bill with substantial defense funding could provide upside. He expects the first quarter of 2027 to be the lightest, with the third and fourth quarters generating substantially more revenue and EBITDA, assuming funding is in place early next year.
Under the Hood: Target Drones to Hypersonics
Kratos is the primary unmanned aerial target drone provider for the U.S. Air Force, Navy, Army and several allied defense agencies. Its portfolio spans rocket systems, hypersonic vehicles, jet engines for drones and missiles, and virtualized ground systems for satellites. The company recently broke ground on two new facilities in Odon, Indiana, focused on AN/SPY-1 radar systems and HELIOS hypersonics testing, supported by $35 million from the Department of War’s Industrial Base Analysis and Sustainment program.
DeMarco confirmed a low-rate initial production contract for the Valkyrie drone following a successful European flight with partner Airbus, though contract details remain restricted. He said Valkyrie revenue is beginning to factor into 2027 guidance and expects additional orders in 2027, including international deals. The company plans to roughly triple Firejet production capacity in Oklahoma City by the end of 2027.
Space and Microwave Growth
The space segment is providing a parallel growth vector. On November 9, Kratos announced a contract with Gulf Space Technology, formerly Thaicom, to deliver the first Q/V/Ka-band gateway antenna systems for the THAICOM 10 software-defined satellite. The turnkey gateway includes antennas, RF equipment, fiber-optic transport, timing subsystems and a monitoring-and-control system with automated weather-fade diversity switching. The Q/V/Ka-band offers roughly two to three times the bandwidth of traditional Ka-band high-throughput satellites.
This builds on a multi-million-dollar ground system award from September 2024 for the THAICOM 10 Satellite Operations Center. The new gateway is designed to exploit the satellite’s ability to dynamically adjust capacity, coverage and service configuration on orbit.
Peer Comparison and Market Context
The divergence in peer performance underscores the sector’s fragmentation. Teledyne Technologies shares rose 0.8% over the same month, buoyed by space-sector demand for its advanced infrared technology and specialized semiconductors. AeroVironment, another unmanned systems player, fell 17.8%, tracking Kratos almost tick for tick.
The detail that matters: Kratos booked $1.04 billion in a single quarter against $471.8 million in revenue, yet the market priced in the political friction of a continuing resolution and an uncertain appropriations timeline. DeMarco’s comment that the internal forecast exceeds the public one by a considerable margin suggests the execution capacity is there; the variable is purely the timing of congressional action.
Sources
- Kratos Defense Stock Declines 17.1% in a Month: Should You Buy the Dip?
- Kratos Defense & Security Solutions
- Kratos Defense & Security Solutions Q3 Earnings Call Highlights
- Kratos Awarded Contract to Deliver Fully Integrated Q/V/Ka-Band Gateway and Antenna Systems for Gulf Space Technology’s Software-Defined Satellite
- Kratos Wins THAICOM 10 Gateway Contract From Gulf Space Technology
- Defense Physical AI Roundup: Shield AI Strikes $5.3B Echodyne Deal as Axon Puts $1.2B Into Skydio
Photo: Holly Jordan (Public domain)