A Record Backlog Built on Rearmament
RTX Corp. has raised its full-year 2026 adjusted earnings per share forecast to a range of $7.65 to $7.75, up from a previous projection of $7.10 to $7.25. The move comes as the company reports a record backlog of $340 billion, driven by over $81 billion in new commercial and defense awards. CEO Chris Calio stated that demand for the company’s products remains strong, citing this surge in orders as the primary driver for the revised outlook. Full-year 2026 revenue is now forecast at $97 billion to $97.5 billion, an increase from the prior estimate of $95 billion to $96 billion.
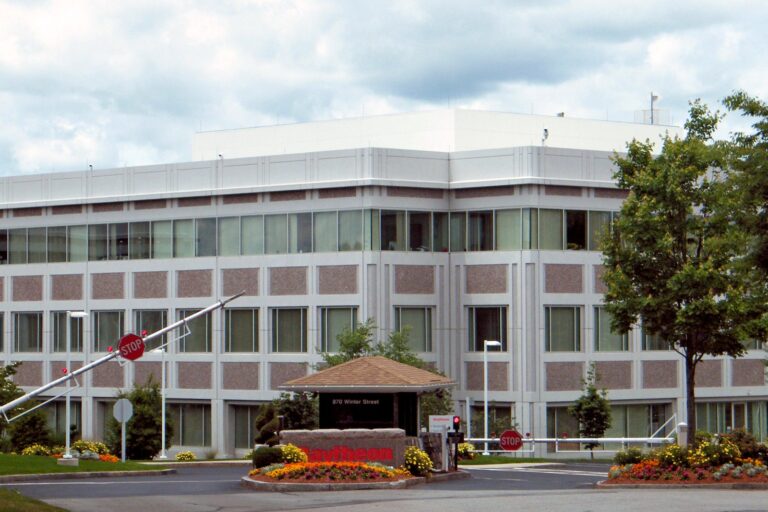
The financial update reflects a broader trend in the global defense sector, where geopolitical uncertainty and ongoing conflicts have created sustained demand for military hardware. RTX, headquartered in Arlington, Virginia, is one of the largest aerospace and defense manufacturers in the world by revenue and market capitalization. The company, formed in 2020 through the merger of United Technologies Corporation and the Raytheon Company, manufactures a wide array of systems including aircraft engines, guided missiles, air defense systems, and satellites. Much of its revenue is derived from the U.S. government, positioning it as a central player in the current rearmament cycle.
Under the hood, the growth is concentrated in the Raytheon division, which serves as the company’s primary weapons manufacturing arm. In the third quarter, Raytheon division sales increased 14% year-on-year to $8.031 billion. The division’s backlog specifically grew to $130 billion, a significant portion of the corporate total. This performance underscores the shift in procurement priorities toward active conflict zones and the need for replenishment of depleted stockpiles. The company’s ability to convert these awards into revenue is now a central focus for investors tracking the defense industrial base.
The Technical Reality of Counter-Drone Sales
A key component of this backlog growth is the expansion of RTX’s counter-drone capabilities, specifically through the Low, slow, small, unmanned aircraft Integrated Defeat System, or LIDS. The company recently secured contracts worth $729 million to deliver key components of LIDS to the U.S. Army, Qatar, and Jordan. These contracts mark the first international sales of Raytheon’s Ku-band Radio Frequency Sensor, known as KuRFS, and its Coyote interceptor systems. The detail that matters here is the geographic expansion of these specific systems beyond the domestic market.
LIDS is designed to counter increasingly sophisticated drone threats by combining advanced radar detection with kinetic and non-kinetic interception capabilities. The system integrates the KuRFS, which provides 360-degree threat detection, with Coyote interceptors capable of defeating both individual drones and coordinated swarms. The contracts include both fixed-site and mobile configurations, offering flexible protection for military installations and deployed forces. Raytheon has noted that the Coyote interceptors have demonstrated effectiveness through hundreds of successful combat interceptions, a statistic that highlights the system’s operational readiness in current conflict environments.
The company’s broader counter-drone portfolio also includes the High-Energy Laser Weapon System, or HELWS. While the KuRFS and Coyote systems rely on radar and kinetic or non-kinetic projectiles, the HELWS uses high-energy photons to detect, track, and neutralize aerial threats. This diversification allows RTX to address different types of unmanned aerial threats, ranging from inexpensive, disposable drones to more complex, coordinated swarm attacks. The technical reality is that modern warfare has shifted the balance toward high-volume, low-cost aerial threats, necessitating a multi-layered defense approach that RTX is currently selling to international partners.
Pressure to Accelerate Production
The surge in orders is occurring against a backdrop of intense pressure from the U.S. Department of Defense to speed up manufacturing and procurement. In August, Deputy Secretary of Defense Steve Feinberg sent a letter to prime contractors stating that traditional years-long development cycles for weapons are “not acceptable.” He emphasized that the U.S. military industrial base must “dramatically accelerate our program schedules and expand our production capacity now.” This directive reflects a strategic shift toward shorter lead times and higher throughput, a change that directly benefits companies with established production lines like RTX.
President Donald Trump and Defense Secretary Pete Hegseth have publicly stated that the U.S. military is well supplied, yet reporting has indicated that the war in Iran has worn down stockpiles of certain key weapons systems. Although the President has repeatedly rejected assertions of shortages, he acknowledged over the summer that supplies for some munitions and weapons systems are “a little bit tighter.” This tension between official statements and reported inventory levels suggests a complex rearmament push is underway, one that requires rapid replenishment rather than long-term development.
For RTX, this environment creates a dual challenge: meeting immediate demand for replenishment while also investing in new technologies. The company’s raised outlook assumes it can navigate this pressure without compromising margins or quality. The $81 billion in new awards represents a significant commitment from customers who are eager to secure hardware in a competitive market. As ever, the ability to scale production quickly will determine whether these record backlogs translate into the sustained profit growth projected for 2026 and beyond.
Market Reaction and Future Outlook
Despite the strong guidance, RTX shares traded down by about 1% on the day of the earnings report. This reaction may reflect investor caution regarding the sustainability of defense spending or the pace at which the company can convert backlog into cash. In contrast, Northrop Grumman shares rose by roughly 5% after the company also raised its 2026 profit outlook. Northrop Grumman projected full-year EPS of $29.35 to $29.75 and sales of $43.75 billion to $44.25 billion. The divergence in market reaction highlights that investors are scrutinizing the specific drivers of growth for each prime contractor.
Defense stocks have largely lagged the S&P 500 so far this year, suggesting that the broader market has not fully priced in the potential for sustained defense spending. Lockheed Martin is expected to report its earnings on Thursday, October 22, which will provide further insight into the sector’s health. The conflicts in Ukraine and the Middle East have proven lucrative for the major defense primes, including RTX, Northrop Grumman, Lockheed Martin, Boeing, and General Dynamics. These companies are benefiting from a global rearmament trend that is likely to persist as geopolitical tensions remain elevated.
Looking ahead, the growth of the anti-drone market is expected to be a significant tailwind for RTX. Mordor Intelligence predicts that the anti-drone market will grow at a compound annual growth rate of 27.83% between 2026 and 2031. This forecast aligns with the company’s strategic focus on counter-unmanned aircraft systems. With a diversified portfolio that includes radar, kinetic interceptors, and laser weapons, RTX is well-positioned to capture a growing share of this market. The technical reality is that the threat of drone warfare is not abating, and the demand for effective countermeasures will remain a central pillar of defense procurement in the coming years.
Sources
- RTX and Northrop Grumman raise 2026 profit outlooks on military rearmament demand – AOL
- RTX Corporation
- RTX Secures $729M LIDS Contracts, Strengthens Counter-Drone Defense
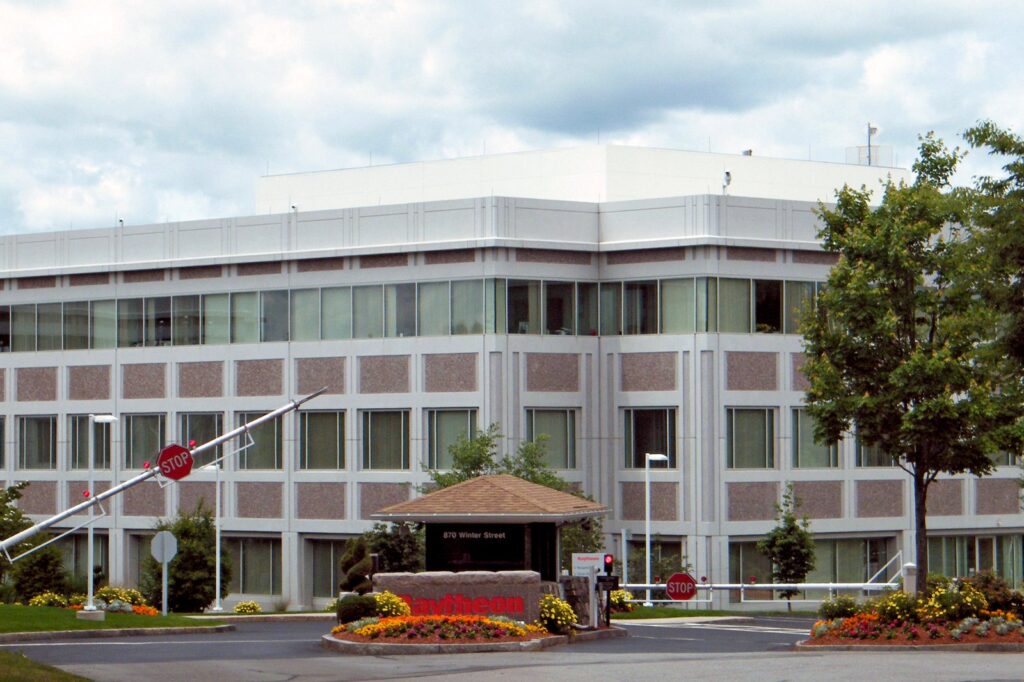
Photo: Coolcaesar at English Wikipedia (CC BY-SA 3.0)